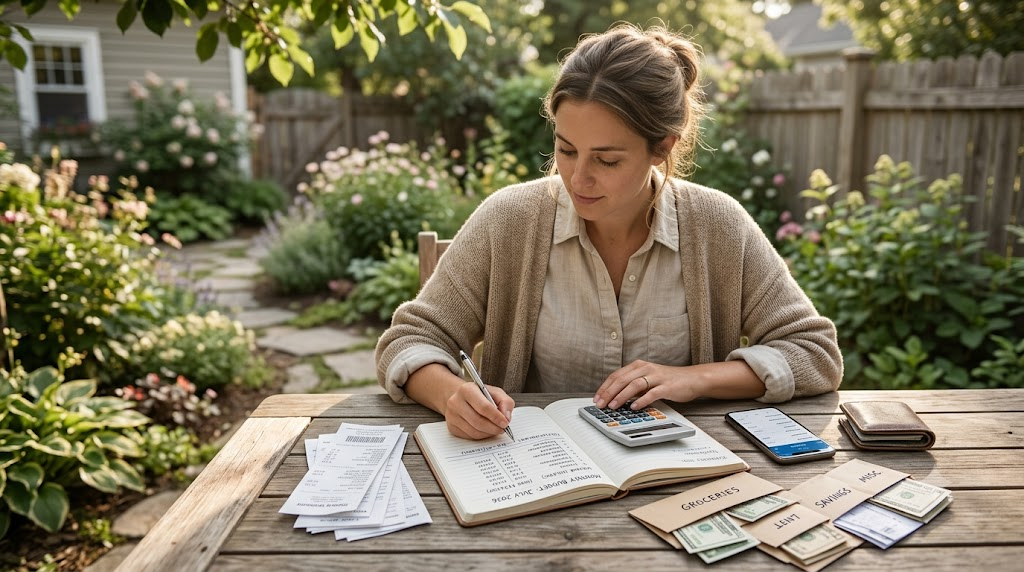

Taking control of your finances often feels overwhelming, but it doesn’t have to be. The foundation of financial freedom isn’t earning a six-figure salary; it’s managing the money you already have. A personal budget is simply a roadmap for your financial journey, giving every dollar a specific purpose so you can stop living paycheck to paycheck and start reaching your goals.
Whether you want to pay off debt, save for a dream vacation, or build a emergency fund, here is a step-by-step guide to creating a practical, effective personal budget.
Step 1: Calculate Your Total Net Income
Before you can plan where your money goes, you need to know exactly how much is coming in. Calculate your net income—the total amount of money that enters your bank account after taxes, health insurance, and retirement contributions are deducted.
- Fixed Salary: Use your take-home pay from your paychecks.
- Variable Income (Freelance/Gig Work): Calculate your average monthly earnings over the last 3 to 6 months to get a realistic baseline.
- Other Sources: Include side hustles, rental income, or child support payments.
Step 2: Track and Categorize Your Monthly Expenses
Next, gather your bank statements, utility bills, and credit card receipts from the past two to three months. Group your spending into two primary categories:
1. Fixed Expenses (Needs)
These are non-negotiable costs that stay relatively constant every month.
- Rent or mortgage payments
- Utilities (electricity, water, internet)
- Loan minimum payments (car loans, student debt)
- Insurance premiums
- Basic groceries
2. Variable Expenses (Wants)
These costs change month-to-month and are often discretionary.
- Dining out and coffee runs
- Entertainment and streaming subscriptions
- Shopping and hobbies
- Gym memberships
Step 3: Choose a Budgeting Method
A budget only works if it fits your personality. Here are three popular methods to consider:
| Budgeting Method | How It Works | Best For |
| 50/30/20 Rule | 50% Needs, 30% Wants, 20% Savings/Debt payoff | Beginners seeking simplicity |
| Zero-Based Budgeting | Every dollar is assigned a job (Income − Expenses = $0) | Detail-oriented planners |
| Envelope System | Cash allocated into physical envelopes per category | People prone to overspending |
For most beginners, the 50/30/20 rule offers a great balance between discipline and flexibility.
Step 4: Subtract Expenses from Income (Set Your Target)
Now, do the math. Subtract your total estimated monthly expenses (Step 2) from your total monthly net income (Step 1).
- If the result is positive: Congratulations! You have a surplus. Allocate the extra cash toward high-interest debt or savings goals.
- If the result is negative: You are spending more than you earn. Review your variable expenses and identify areas to trim down immediately (e.g., canceling unused subscriptions or reducing restaurant meals).
Step 5: Automate Your Savings and Debt Payoff
The easiest way to stick to a budget is to remove willpower from the equation. Treat your savings as a non-negotiable expense.
- Set up automatic transfers: Have a portion of your paycheck move automatically to a separate savings or investment account on payday.
- Automate bill payments: Schedule recurring payments for fixed bills to avoid late fees and protect your credit score.
Step 6: Review and Adjust Monthly
A budget isn’t a static document set in stone; it’s a living system that needs to adapt as your life changes.
- Weekly Check-ins: Spend 5–10 minutes every week tracking your recent purchases to ensure you’re staying within category limits.
- Monthly Review: At the end of the month, compare your planned budget to your actual spending. Adjust your numbers for the upcoming month based on upcoming seasonal expenses, holidays, or income changes.
Conclusion
Creating a personal budget isn’t about restricting your lifestyle or stopping yourself from enjoying life; it’s about spending intentionally on what truly matters to you. By understanding your cash flow, picking a method that matches your lifestyle, and automating your habits, you transform money from a source of stress into a tool for building the life you want.
Start small today: list your income, log your expenses, and take the first step toward financial control.